
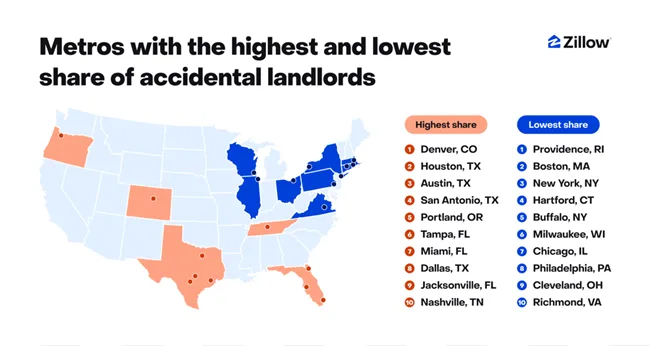
Houston now leads the nation as a hotspot for accidental landlords, outpacing Denver, Austin and San Antonio, according to real estate firm Zillow.
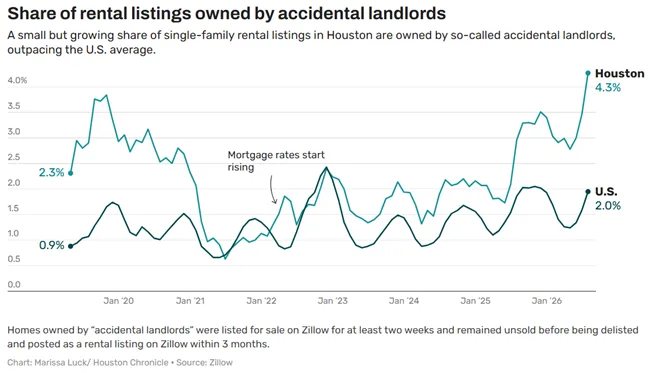
Overall, an estimated 4.3% of single-family rental listings in Houston are properties that owners gave up on selling in the previous three months – triple the rate of three years ago.
“That likely undercounts the rentals that would’ve been sold otherwise had the market been firmer,” said Kara Ng, senior economist at Zillow. “For every homeowner who tried (selling) first, there are likely some who were discouraged by the softer market, bypassed selling, and listed straight into a rental.”
For some homeowners, becoming a landlord is an easy way to generate income. For others, it’s a necessary decision complicated by unexpected costs, frustrating tenants and rents that barely cover their expenses.
Ng said markets with more accidental landlords tend to have a greater supply of for-sale homes with price reductions, longer days on market and less competition among buyers. That’s the case in Houston, where the number of single-family homes hit a record level this summer, according to the Houston Association of Realtors.
The effects are spilling into the rental market. Houston’s supply of single-family, townhomes and condominiums available for lease ballooned by 80% in the past three years – hitting about 16,660 listings in September, according to John Burns Research, not including build-to-rent homes.
During the pandemic, it took less than a month to lease a single-family home, said Kevin Macicek, a broker with property management firm Area Realty. Now it can take up to 60 days, he said.
Ample supply is also keeping a lid on rent prices. And after spiking during the pandemic, rent growth started slowing in 2023. Houston single-family rents average $2,054 today, roughly flat from a year ago, according to John Burns Research.
Clark County Rents Hold Their Ground Against Portland
Newsom Signs Landmark California Pet Policy Transparency Act Into Law